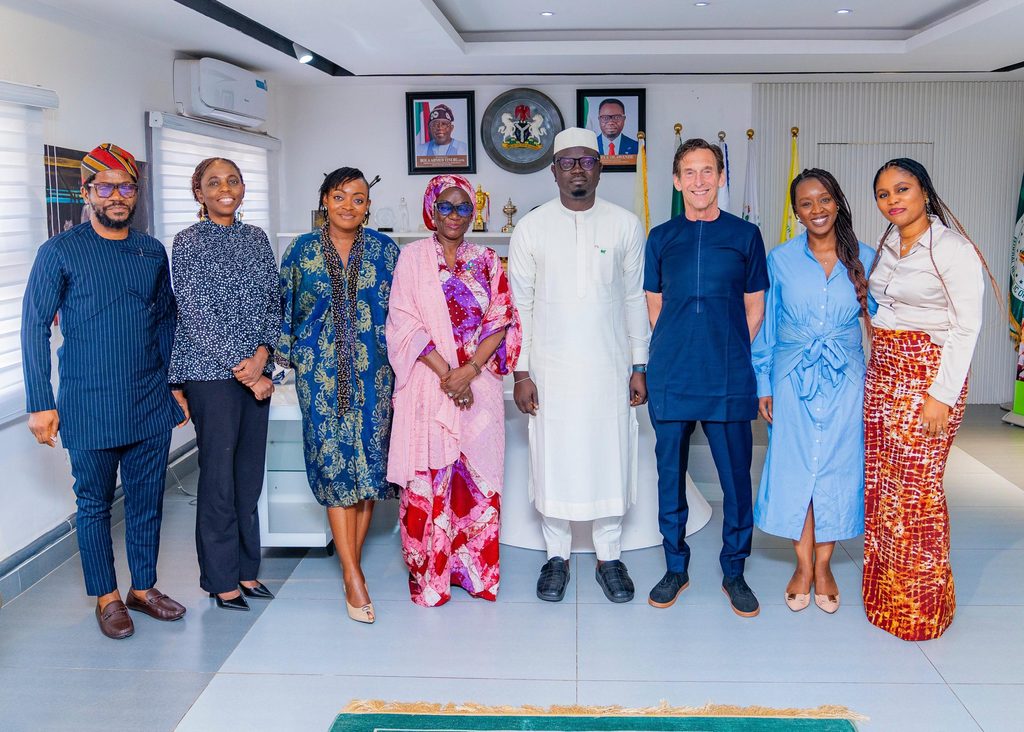
Cascador and Sterling Bank have unveiled a $200 million SME Credit Backstop Fund designed to help Nigerian small and medium-sized enterprises (SMEs) secure larger, longer-term loans and overcome one of the biggest barriers to business growth: access to capital.
The fund is structured to support up to $1 billion in outstanding credit by sharing a defined portion of lending risks with participating financial institutions. The initiative aims to give lenders greater confidence to finance businesses with growth potential but limited access to conventional credit.
The announcement follows Cascador’s white paper, The Multiplier Model, which highlights the mismatch between the financing African businesses need to scale and the capital available to them.
According to the report, only 22% of businesses in Sub-Saharan Africa have a bank loan or line of credit, compared with a global average of 36%.
How the $200 million fund will work
Under the arrangement, Cascador will leverage its network of entrepreneurs and ecosystem partners to identify businesses with scaling potential, while Sterling Bank will contribute its lending infrastructure and credit-market expertise.
The fund will bring together lenders, philanthropic organisations, impact investors and development finance institutions through a shared risk-protection structure.
The process begins with ecosystem partners nominating businesses that meet debt-readiness requirements. Eligible businesses are then screened against the fund’s criteria, including AI-powered underwriting and due diligence. Participating lenders independently assess applications, make lending decisions and remain responsible for disbursement, monitoring and collections.
The initial target is to provide local-currency loans equivalent to $250,000 per business, with the ambition of unlocking loans of up to $1 million as the fund becomes fully capitalised. The structure is also intended to reduce the collateral and guarantee burden for qualifying borrowers, subject to lender approval.
Cascador CEO Trish Thomas said Nigerian entrepreneurs have significant potential but often lack financing that matches their businesses’ stage of development.
Sterling Bank Group Executive Obinna Ukachukwu said the partnership would strengthen the lending process by combining a pipeline of potential borrowers with structured assessments and ongoing monitoring.
A different approach to SME financing
The fund will operate through Riverwell Platform Holding Limited and its Nigerian subsidiary, Riverwell Platform Services Nigeria. The platform will coordinate partners, conduct business-readiness checks, collect data and support portfolio monitoring and reporting, while reserve capital will be held separately.
The model builds on a Catalytic Fund pilot involving Cascador and Sterling Bank over the past two years. The new fund will be independently managed.
The initiative also reflects a broader financing challenge across Africa, where many businesses depend heavily on equity or informal funding because traditional lenders may consider them too risky or lack sufficient information to assess their creditworthiness.
By sharing risk rather than replacing lenders, the fund aims to encourage more debt financing for businesses that can demonstrate their capacity to grow and repay.
What it could mean for Nigerian businesses
If fully funded and successfully implemented, the initiative could help more Nigerian SMEs finance expansion, invest in operations and create jobs without relying exclusively on equity investment.
Cascador says it has supported 80 ventures since 2019, with those businesses collectively raising more than $150 million. In 2025, its alumni served over 1.7 million customers and directly employed nearly 4,000 people.
However, the fund’s potential impact will depend on its final capitalisation, the number of lenders participating, eligibility requirements and how effectively it translates risk protection into actual loans for businesses.
For Nigerian SMEs, the key question is whether this model can make growth financing more accessible, predictable and suitable for businesses ready to scale.